Notes on:
Growth Accounting with Intermediate Inputs
Review of Economic Studies
1 October 1978
growth accounting · productivity · TFP · intermediate inputs · Domar weights · production networks
Paper · doi
Made with AI: Opus 5.5 (reading, diagram and writing), GPT 6.1-Sol (reading), Fable 5.1 (adjudication), GPT 6-Astra (verification)
Charles R. Hulten, Review of Economic Studies 45(3), pp. 511–518 (1978). Published version; no recorded talk.
Charles Hulten’s eight-page paper answers a bookkeeping question that turns out to be a general-equilibrium question: if every sector of the economy has its own productivity residual, how do you add them up into aggregate tfp? The obvious answer is some average, with weights that sum to one, and the paper’s answer is that the obvious answer is wrong in a specific and interesting way. The right weights are gross output over aggregate final demand, they sum to at least one (more, whenever sectors sell to each other), and that is not an accounting quirk but the economics of produced inputs showing up in the arithmetic.
The paper opens with a complaint about how growth accounting scores itself. You compute the residual, divide it by output growth, and call the ratio the share of growth “explained” by productivity. Hulten says this “tends to misstate its true impact”, and the reason is that “some inputs are themselves outputs of the productive process: capital and intermediate input.” If a sector gets more efficient, it makes more stuff; some of that stuff is steel or electricity or machines; and those are inputs somewhere else. The conventional accounting then books the extra steel as input growth, which is to say as not-productivity, even though the only reason the steel exists is the productivity gain. In Hulten’s words, in “any post-mortem assessment of the sources of growth, this induced expansion in produced inputs must be recognized as having been the result of productivity change.”
He had already made this argument for capital in an earlier paper, Hulten (1975), and a footnote here quotes its numbers, which are worth having in your head because they show the size of the stakes. On the Christensen–Jorgenson data for 1948–66, the conventional residual is 1.42% a year and explains only 34% of output growth; once induced capital accumulation is credited to productivity, the adjusted residual is 2.67% a year and accounts for nearly 64%. Those are the 1975 paper’s numbers for capital, not anything computed here. This paper has no data at all. What it does is the parallel move for intermediate inputs, which are less dramatic as a story (nobody writes novels about intermediate deliveries of fertiliser) but more fundamental as a theory, because they pin down what sectoral productivity even means once sectors buy from each other.
Nominal and effective: an incidence analogy
Hulten’s organising distinction is between productivity change originating in a sector and productivity change’s impact on a sector. The first is the shift in that sector’s technology, measured by the ordinary residual. The second is the full equilibrium response to all the shifting technologies, including the reallocation of primary factors between sectors and “the induced expansion in intermediate input, which serves to magnify the effect of technical change.” He says it is the second sense that matters for sources-of-growth questions.
The analogy he reaches for is tax incidence. An excise tax at a statutory rate shifts a supply curve; who actually bears it depends on the equilibrium adjustment, which is what Harberger (1962) built his model to capture. So the residual is the nominal rate of technical change, the statutory rate if you like, and the reduced-form impact is the effective rate. It is a good analogy and a purely conceptual one: no tax appears anywhere in the model, and every price in it is a clean competitive price.
The mechanism: produced inputs loop back
Start at the top, with the whole economy. There is a social production possibility frontier , where is the vector of real final demand (“consumption and investment”) and is the vector of total primary factor supplies. Aggregate productivity change is defined as the outward shift of this frontier holding fixed, which is the right definition if you believe primary factors are the only things the economy is endowed with and everything else is made. Under competitive pricing that shift is measurable:
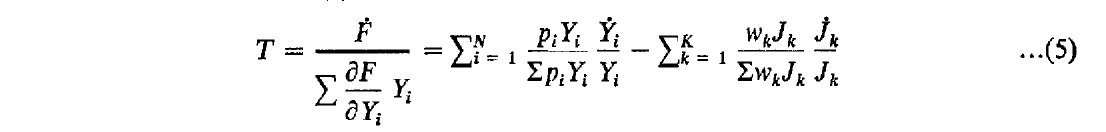
This is eq. 5 in the paper: and are normalised goods and factor prices, final demand for good , the supply of primary factor , so is Divisia final demand minus Divisia primary input, and “can be calculated from price and quantity data.”
(A small honesty note on the printed page. The signs in the frontier’s homogeneity condition and the competitive-pricing conditions, eqs. 2–4, are mutually inconsistent as printed, and taken literally they don’t even deliver factor income equal to final expenditure. The intended convention is that the frontier’s derivative is proportional to in goods and to in factors; the right-hand side above is the economically correct statement, and it is the one to read.)
Now go down to sectors. Production is non-joint and constant-returns: sector makes gross output from intermediate goods (good used in sector ) and primary factors . Log-differentiate, price every input at its marginal product, and you get the standard gross-output residual:
This is eq. 8 in the paper: is gross output of sector and the two sums subtract cost-share-weighted growth of its intermediate and primary inputs, so is the nominal rate, the shift in sector ’s own technology.
Hulten’s gloss on it is exact: it “measures the change in factor efficiency occurring within a sector, but does not measure the impact of the change in efficiency on the growth of that sector.” (A footnote adds that the more familiar value-added residual is valid if and only if technical change enters through a separable primary-input aggregate. That is a condition people still violate cheerfully.)
The link between the two levels is market clearing. Each sector’s gross output goes either to final demand or to other sectors (itself included), , and each primary factor is fully employed across sectors. Log-differentiate those balances, substitute the sectoral residuals into eq. 5, and something pleasant happens: every intermediate flow appears twice, once as an output of its supplier and once as an input of its user, and the two double sums cancel. The primary-input terms cancel against the Divisia input index. What survives is
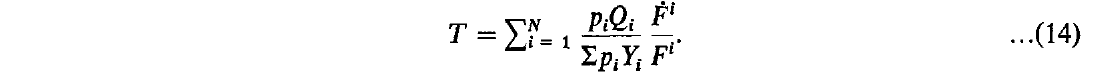
This is eq. 14 in the paper: is the nominal gross output of sector and nominal aggregate final demand (equal to total factor income under constant returns and competitive pricing), so aggregate tfp is the sum of sectoral residuals weighted by sales over gdp.
“This is essentially the aggregation rule proposed by Domar (1961),” Hulten writes, and Domar (1961) had indeed proposed weighting by gross output over final output. What the 1978 paper adds is the proof that this procedure equals the shift of the social production possibility frontier at fixed primary input, in a competitive general-equilibrium economy with arbitrary intermediate linkages. Note how little it needs. No Hicks neutrality, no demand system, no uniqueness of equilibrium: only competitive marginal-product pricing with common prices across users, constant returns, and the adding-up constraints. It is an identity along the equilibrium path, first order in growth rates.
The weights sum to at least one, because for every sector, and strictly more than one as soon as anybody sells anything to anybody else. Hulten’s intuition is the loop in the figure: extra efficiency in sector creates extra ; some of it goes to final demand and some to intermediate deliveries; the deliveries raise output in the using sectors, “and this further increases output, and so on.” So a one-percent residual in steel counts for more than steel’s share of final demand, which is close to zero (you do not buy much steel for consumption), and for exactly steel’s sales relative to gdp.
You can see why any average undercounts. Take an economy where a mining sector sells only to a manufacturing sector, which sells only to households. Mining’s share of final demand is zero, so an average of residuals weighted by final demand gives a one-percent efficiency gain in mining no weight at all; in Hulten’s world it counts at mining’s sales over gdp, because the extra ore turns into extra manufactured goods downstream at no extra primary-factor cost. The double counting that gross-output weights seem to commit is the point, not a mistake.
Effective rates, and an aggregate you can see while its parts stay hidden
Section 4 makes the “impact” sense precise. Close the model with Hicks-neutral sectoral technology, , demand functions for each good, and the assumption that prices and quantities are uniquely pinned down by the exogenous and . Log-differentiating everything gives a linear system (Hulten counts equations, and the endogenous variables do come to the same number), whose reduced form for final demand is . The are “the full equilibrium response in final demand in the th sector to the changing technology of the th sector.” The effective rate keeps only the technology part:
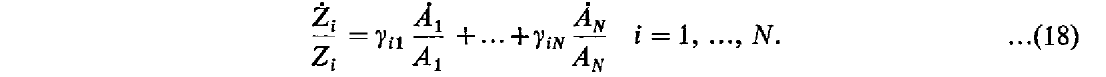
This is eq. 18 in the paper: is the effective rate of productivity change in sector , and the general-equilibrium elasticity of final demand with respect to sector ’s Hicks-neutral technology level .
Here Hulten is admirably blunt about his own object: it “does not, in general, have empirical content since the are complicated functions of various substitution elasticities and commodity shares.” (A footnote points to an exact two-sector, two-factor special case worked out in the trade literature.) So the sector-by-sector “true contribution” of productivity, the thing the introduction said we should care about, is not, in general, something you can compute from the national accounts.
And then the trick. The factor elasticities satisfy a clean adding-up condition that comes from the frontier’s homogeneity together with competitive pricing, (eq. 23 in the paper), which makes all the factor-growth terms drop out when the reduced form is plugged back into the definition of . What is left is
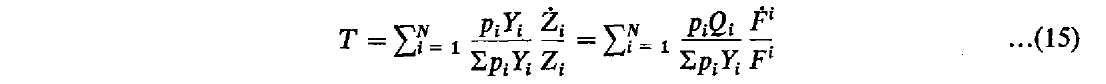
This is eq. 15 in the paper: the final-demand-share-weighted average of the effective rates, which are not in general computable from prices and quantities, equals the Domar-weighted sum of the observable residuals, both equal to the frontier shift .
So the individual effective rates are hidden behind substitution elasticities you don’t know, and their properly weighted average is sitting in plain view in prices and quantities. “The Domar weights produce the same result as productivity change measured in terms of its effect.” One reading of this, which is mine rather than Hulten’s: since eq. 15 holds for any vector of technology growth, the Domar weight of sector must equal the final-demand-weighted column sum of the . The sales share is precisely the one combination of the unknowable general-equilibrium elasticities that the data hand you for free.
Section 5, whose line of proof Hulten credits to the anonymous referee, gets the first equality of eq. 15 without Hicks neutrality, and says non-jointness can be relaxed too. It works through a restricted profit function , homogeneous of degree one in prices and in factors, with Shephard’s lemma giving final supplies and factor prices; with fixed factor supplies, a single consumer (or homothetic preferences), and uniquely determined normalised prices, final demand becomes a function of and alone, and two homogeneity identities make the share-weighted effective rates collapse to . What it generalises is the effective-rate equality. The sectoral residual and the Domar sum are only defined for the non-joint technologies of Section 2; Section 5 offers no joint-production version of them.
The one surprising thing: amplification or neutrality?
If you have met this paper recently, you probably met it as “Hulten’s theorem”, in Baqaee and Farhi (2019), and you met it as a neutrality result. In that later restatement, the first-order effect of a sector’s productivity shock on aggregate output is its sales share, full stop: given sales shares, the shape of the input-output network and all the elasticities of substitution are irrelevant to first order. That is a statement about how little you need to know.
Hulten frames the same identity as an amplification result, and the framing is the opposite emphasis. His introduction says intermediate linkages “magnify the effect of technical change.” The weights sum to at least one. The within-sector residual “does not measure the impact” of efficiency change. His whole motivation is that conventional accounting understates productivity because it hands the credit for induced intermediate (and capital) growth to inputs.
Both readings are one equation. The sales share is simultaneously the multiplier (it is bigger than the final-demand share, by exactly the amount of downstream use) and the sufficient statistic (it is all you need). And the paper does contain the sufficient-statistic content in its own words: “can be calculated from price and quantity data”, and eq. 15 holds even though the have no empirical content. What it never says is that network structure and elasticities don’t matter for the aggregate. That gloss, and the observation that they come roaring back at second order, belong to Baqaee and Farhi. Hulten’s paper also never calls its result a theorem (the only theorem named in it is somebody else’s, in a trade footnote), and its objects are sectoral final demands and a Divisia aggregate at fixed primary input, not a single final good.
It is a nice case of a result changing meaning as the questions around it change. In 1978 the live question was why measured productivity looked so small next to output growth, and the answer was that it is bigger than it looks. Forty years later the live question was whether micro shocks can make macro fluctuations, and the network-origins papers (Gabaix 2011; Acemoglu, Carvalho, Ozdaglar, and Tahbaz-Salehi 2012) used exactly these sales weights as the first-order map from sectoral or firm-level shocks to aggregate tfp, with the network’s job reduced to shaping the distribution of the weights. Empirically, the industry-level gross-output accounting of Jorgenson, Gollop, and Fraumeni (1987) aggregates sectoral residuals with Domar weights, and Hulten’s paper is its standard theoretical justification. All of that is later reading, not anything this paper claims.
For this collection, that is the bridge. If you want to write down an asset-pricing model where aggregate risk comes from sectoral productivity, eq. 14 tells you how to load sectors onto the aggregate shock: by sales over gdp, not by value added and not by final-demand share.
What the result leans on
The objections are mostly the assumptions, which the paper states clearly. Every price is a competitive marginal-product price, the same for every user, so there are no markups, taxes or other wedges; the later literature shows that with wedges the sales-share result breaks (Baqaee and Farhi 2020), and nothing in Hulten’s model speaks to that case. Primary factor supplies are exogenous and price-invariant (held fixed when measuring the frontier shift), so capital is not endogenised here at all; the capital adjustment with its 64% lives in the 1975 paper. The result is continuous-time and first order, an identity in instantaneous growth rates, and the paper says nothing about large or discrete shocks or about how to approximate it with annual data. And the paper delivers the aggregate only: the sector-by-sector effective rates it argues are the conceptually right measure are, by its own admission, not in general recoverable from the data.
Which leaves a slightly funny shape to the whole thing. Hulten set out to say that the conventional sectoral residual is the wrong measure of a sector’s contribution, defined the right one, showed it cannot in general be computed, and then showed that it doesn’t matter, because the thing you actually wanted to aggregate was computable all along from the wrong measure, provided you weight it correctly. That is a better outcome than most correct critiques of measurement get.